
Arthur Dennyson Hamdani
Renovating tenants out of house and home
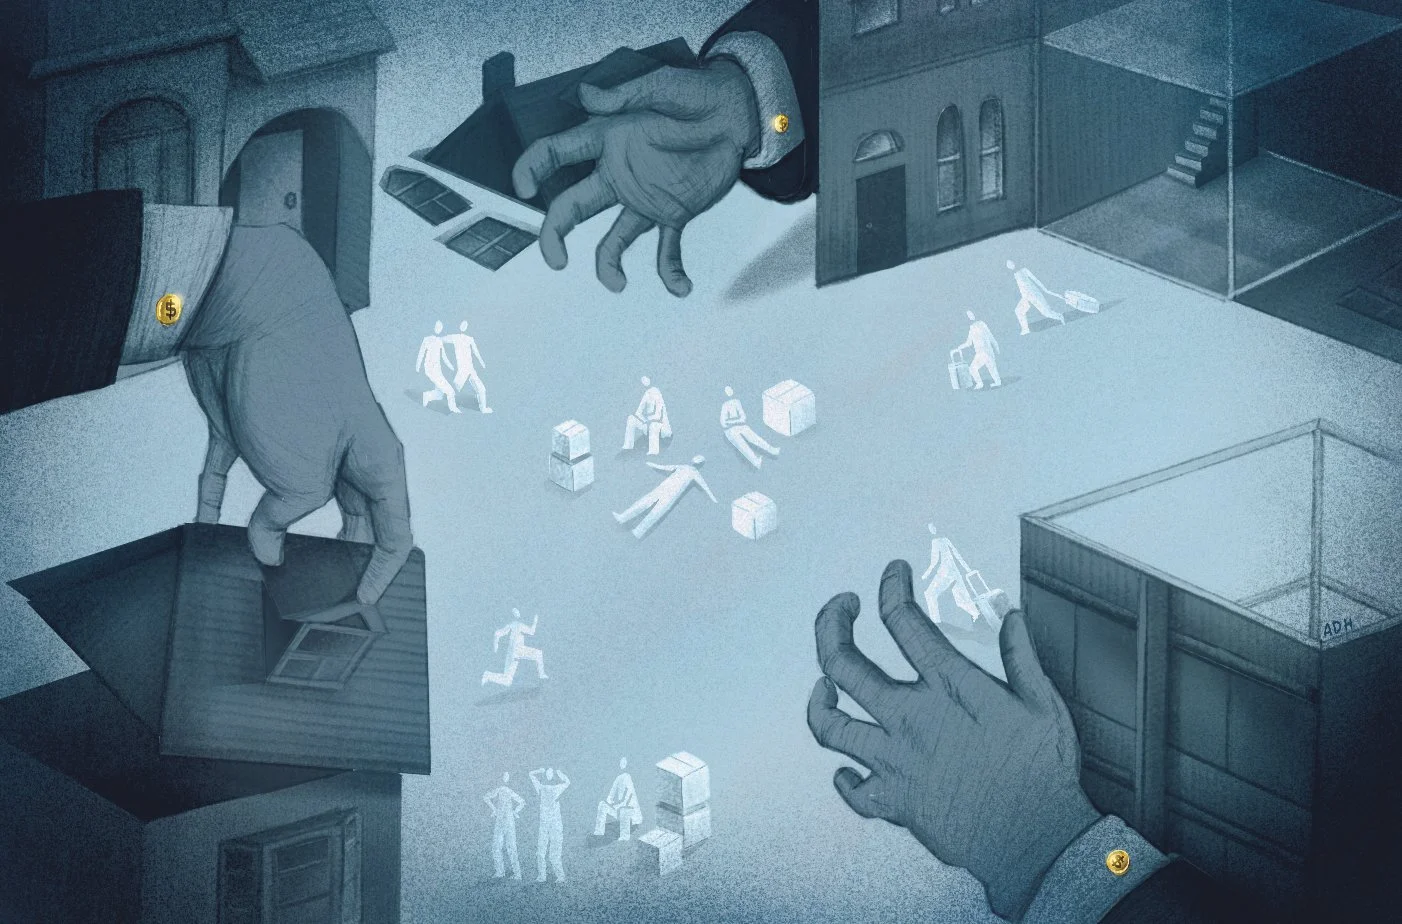
Renovictions are rising as yet another tool in landlords’ eviction kits. These types of evictions are often legally allowed and landlords are exploiting this, further placing tenants in precarity.
By Cole Webber and Philip Zigman
Renoviction, as we use the term, is when a landlord tries to push a tenant out of their home by claiming they will renovate the unit. It is a landlord strategy to permanently displace tenants from rental units based on the claim that they will renovate the empty units. The landlord begins the process of renoviction by notifying the tenant, either verbally or in writing, that they want them to move out. The landlord may then apply financial, physical, and legal pressure on the tenant to push them out of their home. The landlord may issue eviction notices, but they may not. The landlord may or may not renovate common areas of the building or individual units after tenants have moved out. Renoviction is primarily about displacement, not renovations.
While the specific provisions vary, Canadian provinces allow eviction for renovations, and landlords can renovict tenants without breaking any rules or doing anything illegal. In Ontario, a landlord may legally evict a tenant to extensively renovate their rental unit. The Ontario Residential Tenancies Act thus provides a legal framework for renoviction. When landlords do start the legal eviction process by issuing an N13 eviction notice, they frequently do not find it necessary to have evictions enforced through the legal process. This is because the combined pressure of a legal eviction notice with extralegal eviction tactics is often enough to push tenants out. When these tactics get the job done, there is no need for the landlord to file an eviction application with the Landlord and Tenant Board. Landlords do not always issue an N13 notice and initiate the legal eviction process when trying to push tenants out, but there is nothing illegal about, for example, offering tenants buyouts on the condition that they terminate their tenancies. This is not to say that landlords may not break various rules when renovicting tenants, only that it is misguided to characterize renovictions as cases where tenants are evicted “illegitimately” or “illegally.” Landlords renovict and therefore permanently displace tenants even when they follow the rules or refrain from breaking any laws.
Our understanding of renoviction is supported by the economic realities of rental housing in Toronto and across the country, how renovictions actually unfold, and public statements made by landlords.
Many long-term tenants throughout Toronto are paying around $1,000 per month for a one-bedroom or two-bedroom apartment. Meanwhile, the average asking rent for a vacant one-bedroom in the city over the past few years has been around $2,300 to $2,500. The removal of sitting tenants from their homes under these conditions not only allows landlords to significantly increase their rental revenues, it can also increase the value of the property as a result of these higher rents.
Landlords who use the renoviction strategy often look to urban areas where they anticipate rapid future rises in land value. They purchase older, undercapitalized, low- to medium-density rental buildings from smaller, less profitable companies. They acquire buildings with a high proportion of long-term tenants paying rents that are significantly lower than asking rents for vacant units in the area. Why would a landlord buy such a building? Because they can make a lot of money by closing the rent gaps. Additional investment in the form of extensive renovations can also result in significant returns, so long as rents are raised.
Ads and brochures for multi-family rental buildings in Toronto that are for sale often highlight rent gaps and “rental upside.” Brochures will often note the “gap to market,” or the average difference between rents for tenants currently in the building and market rents for the area, and how much rents can be increased if a property is “repositioned” – such properties are sometimes called “value-add.” Salespeople highlight these features because they know that is what their clients are seeking. Low rents in a building are attractive not because investors like low revenues but because they mean the property’s value is lower due to these rents. Long-term tenants paying lower rents are not normally looking to move – if anything because they can’t afford to – so landlords have to work to get tenants out and turn over units. Sometimes this is put in terms of “active management,” whereby a building that is “undermanaged” is one where tenants are not being actively pushed out. Often landlords will seek to acquire these types of older buildings with lower rents even before they hit the market and are advertised to the public.
Landlords who renovict tenants cite the desire to renovate the vacant unit as the reason for forcing people out and draw from a consistent playbook of tactics well suited to displacing tenants from low- to medium-density rental properties. The number of landlords using the renoviction strategy in Toronto and other cities appeared to be growing in recent years, and many replicate it over and over in buildings they acquire. This warrants inquiry into the specific practice. And it is impossible to understand renoviction without appreciating the real estate context in which it takes place. Real estate investors are not interested in spending $10,000 or $50,000 to upgrade a two-bedroom apartment for a tenant who is paying $1,200 a month in rent. But if the landlord can double the rent for a new tenant and sell or refinance the property following extensive renovations, then that expense becomes a worthwhile investment.
Most landlords who renovict tenants try to avoid attention. They understand how the public generally feels about what they are doing, so they keep a low profile. But some landlords who use the renoviction strategy are more open about their approach to real estate investment.
Lankin Investments and Riley Real Estate Ventures (RREV) are two landlords with a track record of renoviction who market themselves to potential investors based on the profitability of the strategy. Since both firms have made recent public statements about their business models, we will quote from them at length.
Lankin Investments, founded by the father and son duo Brian and Kyle Pulis and formerly known as Pulis Investments, is a rental housing investment firm involved in the “strategic acquisition and renewal of undervalued and underperforming apartment buildings.” In early 2022, Lankin bought the mid-rise apartment building at 1570 Lawrence Avenue West in north Toronto and issued N13 eviction notices to the building’s ground-floor tenants. The following month, Lankin issued an offering memo to potential investors that outlined their investment strategy and provided information about the properties owned by what the memo refers to as the “Partnership.”
The firm seeks to “create value” by purchasing properties they deem undervalued, conducting renovations, refinancing “to realize immediate market value gains,” and using those funds to acquire new properties. Of course, Lankin Investments seeks to increase rents following renovations. This is only possible if renovated units are rented to new tenants (or, theoretically, old tenants signing new leases). In their offering memo, they note how many units in each of their properties have been renovated to date, as well as the pre-renovation rents and post-renovation rents. In many of the properties, more than half of the units have been renovated in only a few years. Often, rents in the buildings double following renovations.
The memo, as well as earlier Lankin Investments memos going back to 2016, also stated the following with respect to its properties:
As the Partnership intends to vacate all apartment units in the Property and reposition the Property by performing significant renovations and improvements in order to lease the Property to a new demographic of tenants, the future rents, vacancy, expense, cost, and other financial information concerning the Current Properties are expected to be materially different than the historical information disclosed herein.
Here, Lankin Investments articulates most clearly the strategy that is described and suggested elsewhere in the memo and the firm’s promotional materials. The different tactics Lankin Investments uses to push tenants out of their homes in order to turn over units have been well documented.
In a 2021 interview, Jason Thomsen of Lankin Investments elaborated on the business model:
The revenue that we generate from these assets increases pretty significantly, and as a result, the value of the assets also increases. Once the value of the asset is increased substantially, what we do is we employ a program of refinancing. Refinancing basically allows us to capture equity growth that has occurred in those assets over a period of time, allows us to withdraw that equity by taking on a larger mortgage, and we use that equity to roll into new acquisitions. It really creates a compounding effect for the fund, allowing us to deploy more capital year over year, allowing us to acquire more buildings which then go through the same value-add model.
In the interview, Thomsen goes on to explain just how profitable the business model can be. In 2016, Lankin bought the thirty-four-unit building at 44–52 Hayden Street in Hamilton for $3.3 million. In 2016, the average rent for a two-bedroom apartment in the building was $770. By 2021, two-thirds of the original tenants had been removed from the building and average rents had more than doubled, to $1,700. Thomsen notes that each “unit turn” has added $220,000 to $250,000 to the building’s equity value. In 2020, the building was assessed at a total value of $9.02 million. Thomsen underlines Lankin Investments’ unit-by-unit approach to closing rent gaps: “It is a significant value-add model which generates pretty strong results in a relatively short period of time [...] there are still about ten units left to go, so there’s additional upside to be had.”
RREV, founded by Brendan Riley, is a smaller outfit that got its start in the single-family house-flipping business before expanding into the acquisition of purpose-built rental properties. In 2021, RREV bought the twelve-unit low-rise building at 2419 Keele Street in north Toronto and issued N13 eviction notices to all tenants living there. Tenants of 2419 Keele responded with a successful campaign that stopped the evictions, and Riley has since shuttered RREV.
On its website, RREV spelled out its business model to investors:
Working closely with our extensive industry network, our mission is to acquire undervalued properties, efficiently execute on extensive renovations, stabilize the building at today’s market rent rates resulting in us refinancing or selling the property. The proven and efficient process will ensure that we can continually guarantee the capital returns expected from our investors.
Referring to the model as “proven” suggests RREV had executed it multiple times before. And thanks to media coverage, we know of one other case for sure, at 1 Kingswood Road in east Toronto. The company at one point also listed newly renovated apartments for rent at a few other low-rise apartment buildings throughout Toronto. When asked why he had issued eviction notices for extensive renovations to tenants at the Kingswood Road building, Riley explained his approach this way: “We are improving the quality of the building and therefore the quality of the tenants that will be living there in the future.”
As with Lankin Investments, renoviction is central to RREV’s business model. Tenants are not pushed out as a by-product of renovation work. Rather, renovations are conducted so that rents can be raised to market rates, which is only possible if tenants are permanently displaced. This is done to provide returns for investors. In one Facebook post, RREV claims to “help create environments of opportunity [...] by unlocking the value of underperforming properties across the GTA. We have helped countless partners build passive income and reach financial freedom through safe, secure investments in #realestate.”
Another post explains how RREV “unlocks” this value through the “#BRRRRMethod: Buy, Rehab, Rent, Refinance, Repeat.” In a video posted to the RREV YouTube channel, Shane Newman, director of finance, shared this candid reflection on why investors are attracted to RREV’s business model:
They see us as opportunistic. It has somewhat of a negative connotation sometimes, but in this situation we are opportunistic. We’re looking at opportunity in the marketplace that pretty much no one else has jumped on. And we’re extracting the maximum amount of value we can on that opportunity.
Though RREV is one of the few firms publicly advertising how they want to exploit such “opportunity in the marketplace,” Newman was wrong to think that they were virtually alone in executing the strategy. This is made clear by the number of buildings in Toronto and elsewhere where tenants face renoviction and the similarities in how these renovictions are carried out, as well as the number of individuals and firms who have used the strategy across different buildings.
Landlords renovict tenants to close rent gaps and increase the value of their properties. Many will then leverage this value to acquire more rental properties, where they can deploy the strategy again. Vacancy decontrol and rent regulations across provinces establish the legal framework through which the closing of rent gaps is profitable on a per unit basis. Landlords attract further capital investment by demonstrating to potential investors that their renoviction strategy is quick and cost-effective and may be carried out across multiple properties simultaneously. In this way, over time, landlords may increase the scale at which they deploy the renoviction strategy.
Abridged excerpt from Renovictions and Resistance in the Capitalist City by Cole Webber and Philip Zigman (Between the Lines, 2026); reprinted with permission.
Cole Webber is a community legal worker at Parkdale Community Legal Services in Toronto.
Philip Zigman is a co-creator of RenovictionsTO.